- Home
- Strategies
- All Strategies
- Bear Put Spread: Payoff, Breakeven and Example
Strategy guide
Bear Put Spread: Payoff, Breakeven and Example
Profit from a falling stock for a fixed, small debit. The short put pays for part of the long put and caps the gain.
7-day free trial, cancel any time.
What is a bear put spread?
A bear put spread is a bearish options trade made of two puts on the same stock with the same expiration: you buy a put at a higher strike and sell a put at a lower strike. You pay a net debit up front. The spread gains value as the stock falls and turns a profit once the stock is below the breakeven, the higher strike minus the debit.
It is also called a debit put spread or a long put spread. "Put spread" can also mean the bull put spread, which is sold for a credit.
Quick take. Example: buy the 200 put at $6.50 and sell the 190 put at $2.69 for a $3.81 debit. The most you can lose is $381 a contract, the most you can make is $619, and the breakeven at expiration is $196.19.
A bear put spread buys a higher-strike put and sells a lower-strike put for a net debit; the most it can lose is the debit and the most it can make is the strike width minus the debit.
At a glance
- Difficulty
- Beginner
- Capital needed
- The net debit
- Risk profile
- Bearish, Defined Risk, Debit Strategy
- Compare with
- Bear Call Spread, Debit Spread, Bull Put Spread
ApexVol Terminal
Options analytics, live.
Chains, IV rank, expected move and dealer positioning for 5,500+ US stocks and ETFs.

- Live chains and Greeks
- IV rank and percentile
- Expected move and GEX
- Screener and strategy P&L
Free on AAPL, no account. Trial: no charge if you cancel before it ends.
Run the numbers before you trade. Payoff chart, breakeven and Greeks for any options trade. Free, no signup.
Options profit calculatorHow a bear put spread works
The strategy has two legs: you buy one put option at a higher strike and sell one put at a lower strike, on the same stock with the same expiration. The put you buy gains as the stock falls. The put you sell pays for part of it, and in return you give up any gain below its strike.
Because you pay to open it, it is a debit spread. It is one of the two ways to build a bear spread: using puts, as here, costs money up front, while the bear call spread uses calls and pays you a credit.
The three numbers that define it
- Max loss is the net debit you paid. You lose all of it if the stock is at or above the higher strike at expiration.
- Max profit is the width between the strikes minus the net debit, reached at or below the lower strike.
- Breakeven is the higher strike minus the net debit.
Where the stock finishes decides the result
- Above the higher strike: both puts expire worthless and you lose the debit.
- Between the strikes: the long put is in the money and the short put is not, so the spread is worth the higher strike minus the stock price.
- Below the lower strike: both puts are in the money and the spread is worth the full width between the strikes.
Bear put spread example
A hypothetical trade with round inputs, so the arithmetic is easy to follow. The option prices come from the Black-Scholes model with the inputs below; real quotes will differ.
- Stock at $200, 45 days to expiration, implied volatility 25%, interest rate 4%, no dividend.
- Buy the 200 put at $6.50.
- Sell the 190 put at $2.69.
- Net debit: $6.50 - $2.69 = $3.81 a share, or $381 for one contract of 100 shares.
| Result | Per share | Per contract | How it is worked out |
|---|---|---|---|
| Max profit | $6.19 | $619 | $10 width minus the $3.81 debit, at $190 or below |
| Max loss | $3.81 | $381 | The debit, at $200 or above |
| Breakeven | $196.19 | 200 minus 3.81 |
That is $619 of possible profit against $381 of risk, about 1.6 to 1. All figures on this page leave out commissions and fees, which lower the profit and raise the breakeven slightly.
Profit and loss at expiration
| Stock at expiration | 200 put worth | 190 put worth (you owe) | Spread worth | P&L per contract |
|---|---|---|---|---|
| $180 | $20.00 | $10.00 | $10.00 | +$619 (max profit) |
| $190 | $10.00 | $0.00 | $10.00 | +$619 (max profit) |
| $193 | $7.00 | $0.00 | $7.00 | +$319 |
| $196.19 | $3.81 | $0.00 | $3.81 | $0 (breakeven) |
| $200 | $0.00 | $0.00 | $0.00 | -$381 (max loss) |
| $210 | $0.00 | $0.00 | $0.00 | -$381 (max loss) |
To try other strikes or prices, open this exact spread in the debit spread calculator and change any input.
Bear put spread payoff diagram
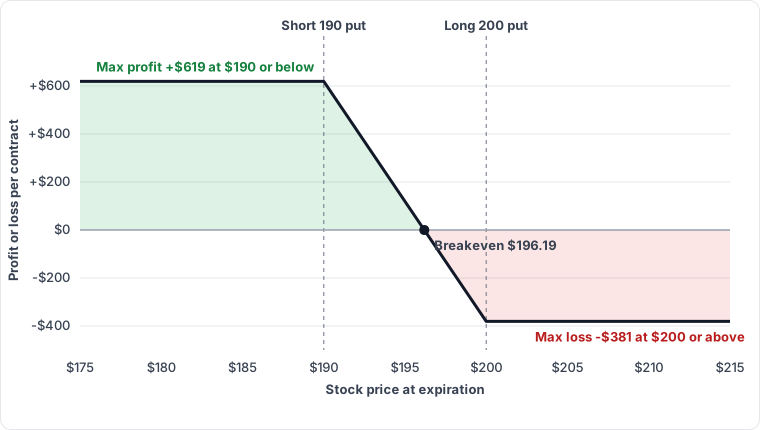
Losses stop at the debit however far the stock rallies, which is the main difference from shorting 100 shares, where a rally has no ceiling on the loss. Gains stop at the lower strike however far the stock falls. Between the strikes the line is straight: each $1 the stock drops adds $100 to a one-contract position.
Why use a spread instead of buying the put
Selling the lower put cuts the cost and cuts how much the position cares about implied volatility. The same example on the day you open it, per contract:
| Lone 200 put | 200/190 bear put spread | |
|---|---|---|
| Cost | $650 | $381 |
| Breakeven at expiration | $193.50 | $196.19 |
| Most it can make | $19,350 (stock to zero) | $619 |
| Gain for a $1 drop today (delta) | $46 | $21 |
| Change for 1 point of implied volatility (vega) | $27.90 | $5.70 |
| Time decay per calendar day (theta) | -$6.70 | -$1.10 |
The spread costs 59% as much as the put but keeps only about 20% of its sensitivity to implied volatility. If implied volatility rose 5 points right after you opened, the lone put would gain about $140 and the spread about $25. The case to plan for is the reverse: if implied volatility is high when you open and then falls, for example after an earnings report (see IV crush), the lone put gives back far more than the spread.
That makes the spread a better fit than a lone put when options are expensive. Against a bear call spread it is the other way round: the credit spread gains when implied volatility falls, so high implied volatility favours it. Before choosing, check where implied volatility sits against its own past year with IV rank and IV percentile.
Choosing strikes and expiration
Put the long strike at or near the current price so the spread gains value from the first dollar the stock falls. Put the short strike where you expect the stock to be at expiration: the spread earns the most there, and you are not paying for a move past your target.
| Per contract | 200/190 | 200/180 |
|---|---|---|
| Net debit | $381 | $567 |
| Max profit | $619 | $1,433 |
| Reward to risk | 1.6 to 1 | 2.5 to 1 |
| Breakeven | $196.19 | $194.33 |
A wider spread pays more if the stock really falls, but it costs more and needs a bigger drop to break even. A narrower one is cheaper and breaks even sooner. Moving both strikes below the stock price makes the spread cheaper and more bearish, since the stock has to fall further before it pays anything.
For expiration, the question is how long the move needs. More time costs more but gives the stock room to get there. If you expect the drop within days, a short expiration is cheaper; for a slow drift lower over weeks, buy more time.
How time decay changes as the stock moves
Time decay works against a bear put spread when the stock is above the strikes and for it once the stock is below them. The same 200/190 spread with 20 days left:
| Stock price | Spread worth | Time decay per calendar day, per contract |
|---|---|---|
| $210, above both strikes | $1.08 | -$5.30 |
| $195, between the strikes | $4.95 | about $0 |
| $185, below both strikes | $8.04 | +$5.70 |
Above the long strike, the long put is closer to the money and loses value faster than the short put. Below the short strike it is the other way round, so each day that passes adds value. That is why a stock that falls early and then stalls is a good outcome for this trade.
Managing and closing a bear put spread
How to close it
Close both legs together as one spread order: sell the 200 put to close and buy the 190 put to close. Your broker quotes the spread as a single price, which is what it is worth now. One order avoids being left holding a single leg if the price moves between fills.
When to take profit
In the example, with 20 days left and the stock at $185, the spread is already worth $8.04 of its $10.00 maximum. Holding to expiration can add at most $1.96 a share while leaving 20 days for the stock to bounce. Closing once most of the maximum is in hand gives up a little profit to take that risk off the table.
Rolling or adjusting
If the stock has already fallen to your short strike and you expect more downside, you can roll down: close this spread and open a new one with lower strikes, paid for partly by the profit on the first. If the stock has risen against you and your view has not changed, rolling to a later expiration costs a new debit, so it adds to the amount at risk rather than repairing the trade. Decide the most you will spend on one view before you start.
What happens at expiration
- Stock above $200: both puts expire worthless. There is nothing to do, and the debit is lost.
- Stock between $190 and $200: the 200 put is in the money and is usually exercised, which leaves you short 100 shares at $200, while the 190 put expires. Close the spread before expiration if you do not want that stock position. If the stock closes right at $190, you may not know until the next day whether the 190 put was assigned, so closing before the bell removes that doubt too.
- Stock below $190: your 200 put is exercised and the 190 put is assigned, so you sell 100 shares at $200 and buy 100 at $190. No shares are left, and the $10 difference is the full value of the spread.
Early assignment
Only the short put can be assigned early, and it is most likely when that put is deep in the money with almost no time value left. If it happens you buy 100 shares at $190, which is $19,000, so the account needs the cash or margin for that until the shares are gone; a margin call is possible if it does not have it. You can sell the shares and keep or sell the 200 put, or exercise the 200 put to sell the shares at $200. Exercising locks in the full $10 width but gives up any time value left in the 200 put, so compare the put's market price with its exercise value first.
Bear put spread vs bear call spread
Both are bearish spreads with a fixed maximum loss.
| Bear put spread | Bear call spread | |
|---|---|---|
| Built with | Buy the higher put, sell the lower put | Sell the lower call, buy the higher call |
| Cash at the open | You pay a debit | You receive a credit |
| Makes the most when | The stock falls to the lower strike or below | The stock stays below the lower strike |
| Time passing | Hurts above the strikes, helps below them | Helps while the stock stays below the short strike |
| Implied volatility rising | Small gain near or above the long strike; flips to a small loss below the short strike | Small loss near or below the short strike; flips to a small gain above the long strike |
| Best fit | You expect a real drop | You expect the stock to stall or drift lower |
There is no bearish put spread that pays a credit. A put spread opened for a credit is the bull put spread, which profits when the stock stays up. If you want a bearish trade that pays you up front, use the bear call spread.
Other names, and the other kind of put spread
This trade is also called a debit put spread, a long put spread or a bear put debit spread.
"Put spread" on its own can mean either of two trades. The bearish one, bought for a debit, is this page. The bullish one, sold for a credit, is the bull put spread: the same two puts with the sides swapped, selling the higher strike and buying the lower one. The debit spread guide covers the bear put spread alongside its bullish twin, the bull call spread.
Try this with real market data. 5,500+ stocks, live options chains, IV analytics and P&L. 7-day free trial.
- Written by
- ApexVol Research Team
Quantitative options research. - Reviewed by
- Ryan Silk, ApexVol Founder
Reviewed for technical accuracy. 10+ years trading options; built ApexVol's pricing engine, Greeks model and IV-rank methodology.
Revised as market conditions and institutional data change. Last revised 2026-11-15. How we research →
Questions
About the bear put spread.
Is a bear put spread a debit or a credit spread?
A debit spread. You pay to open it because the put you buy, at the higher strike, costs more than the put you sell at the lower strike.
What is the max profit on a bear put spread?
The width between the two strikes minus the debit you paid, earned if the stock is at or below the lower strike at expiration. A $10-wide spread bought for $3.81 can make $6.19 a share, or $619 a contract.
What is the breakeven on a bear put spread?
The higher strike minus the net debit. For a 200/190 spread bought for $3.81, the breakeven at expiration is $196.19.
How do you close a bear put spread?
Enter one spread order that sells the long put to close and buys the short put to close. Closing both legs together avoids holding a single leg if the price moves between fills.
What happens if the stock ends between the strikes?
The long put is in the money and is usually exercised, which leaves you short 100 shares, while the short put expires. Closing the spread before expiration avoids that stock position.
When should I use a bear put spread instead of buying a put?
When you expect a moderate drop and options are expensive. The spread costs less and is much less exposed to a fall in implied volatility, in exchange for capping the profit at the lower strike.
Keep reading
Where this strategy
shows up next.
Strategy notes every week. Strategy breakdowns, risk notes and trade ideas out of our own analytics.
No account needed. Unsubscribe any time.
Practice it before you risk it.
Then trade it for real.
Build the legs in the simulator and read the payoff, the breakevens and the Greeks against a live chain. Run it on AAPL without an account.
Real market data, not a sandbox. See it live on AAPL.